The National Wealth Fund’s £200M commitment to Associated British Ports provides a template for how public capital can group smaller projects, extend the life of the debt and bring commercial lenders into infrastructure that might otherwise move too slowly.
By Ben Mardon, Head of Real Assets, Europe, Gen II Fund Services
A freight terminal, an offshore wind base, a nuclear supply chain project and a defence-linked port upgrade do not look like an obvious financing package.
Put them together, add long-term public debt and £100M from commercial banks and they start to look like a model for getting more UK infrastructure built.
The National Wealth Fund has committed £200M to Associated British Ports through a 17.5-year senior loan. Bank of America, Lloyds and NatWest are providing the remaining commercial finance, creating a £300M package for upgrades across ABP’s network.
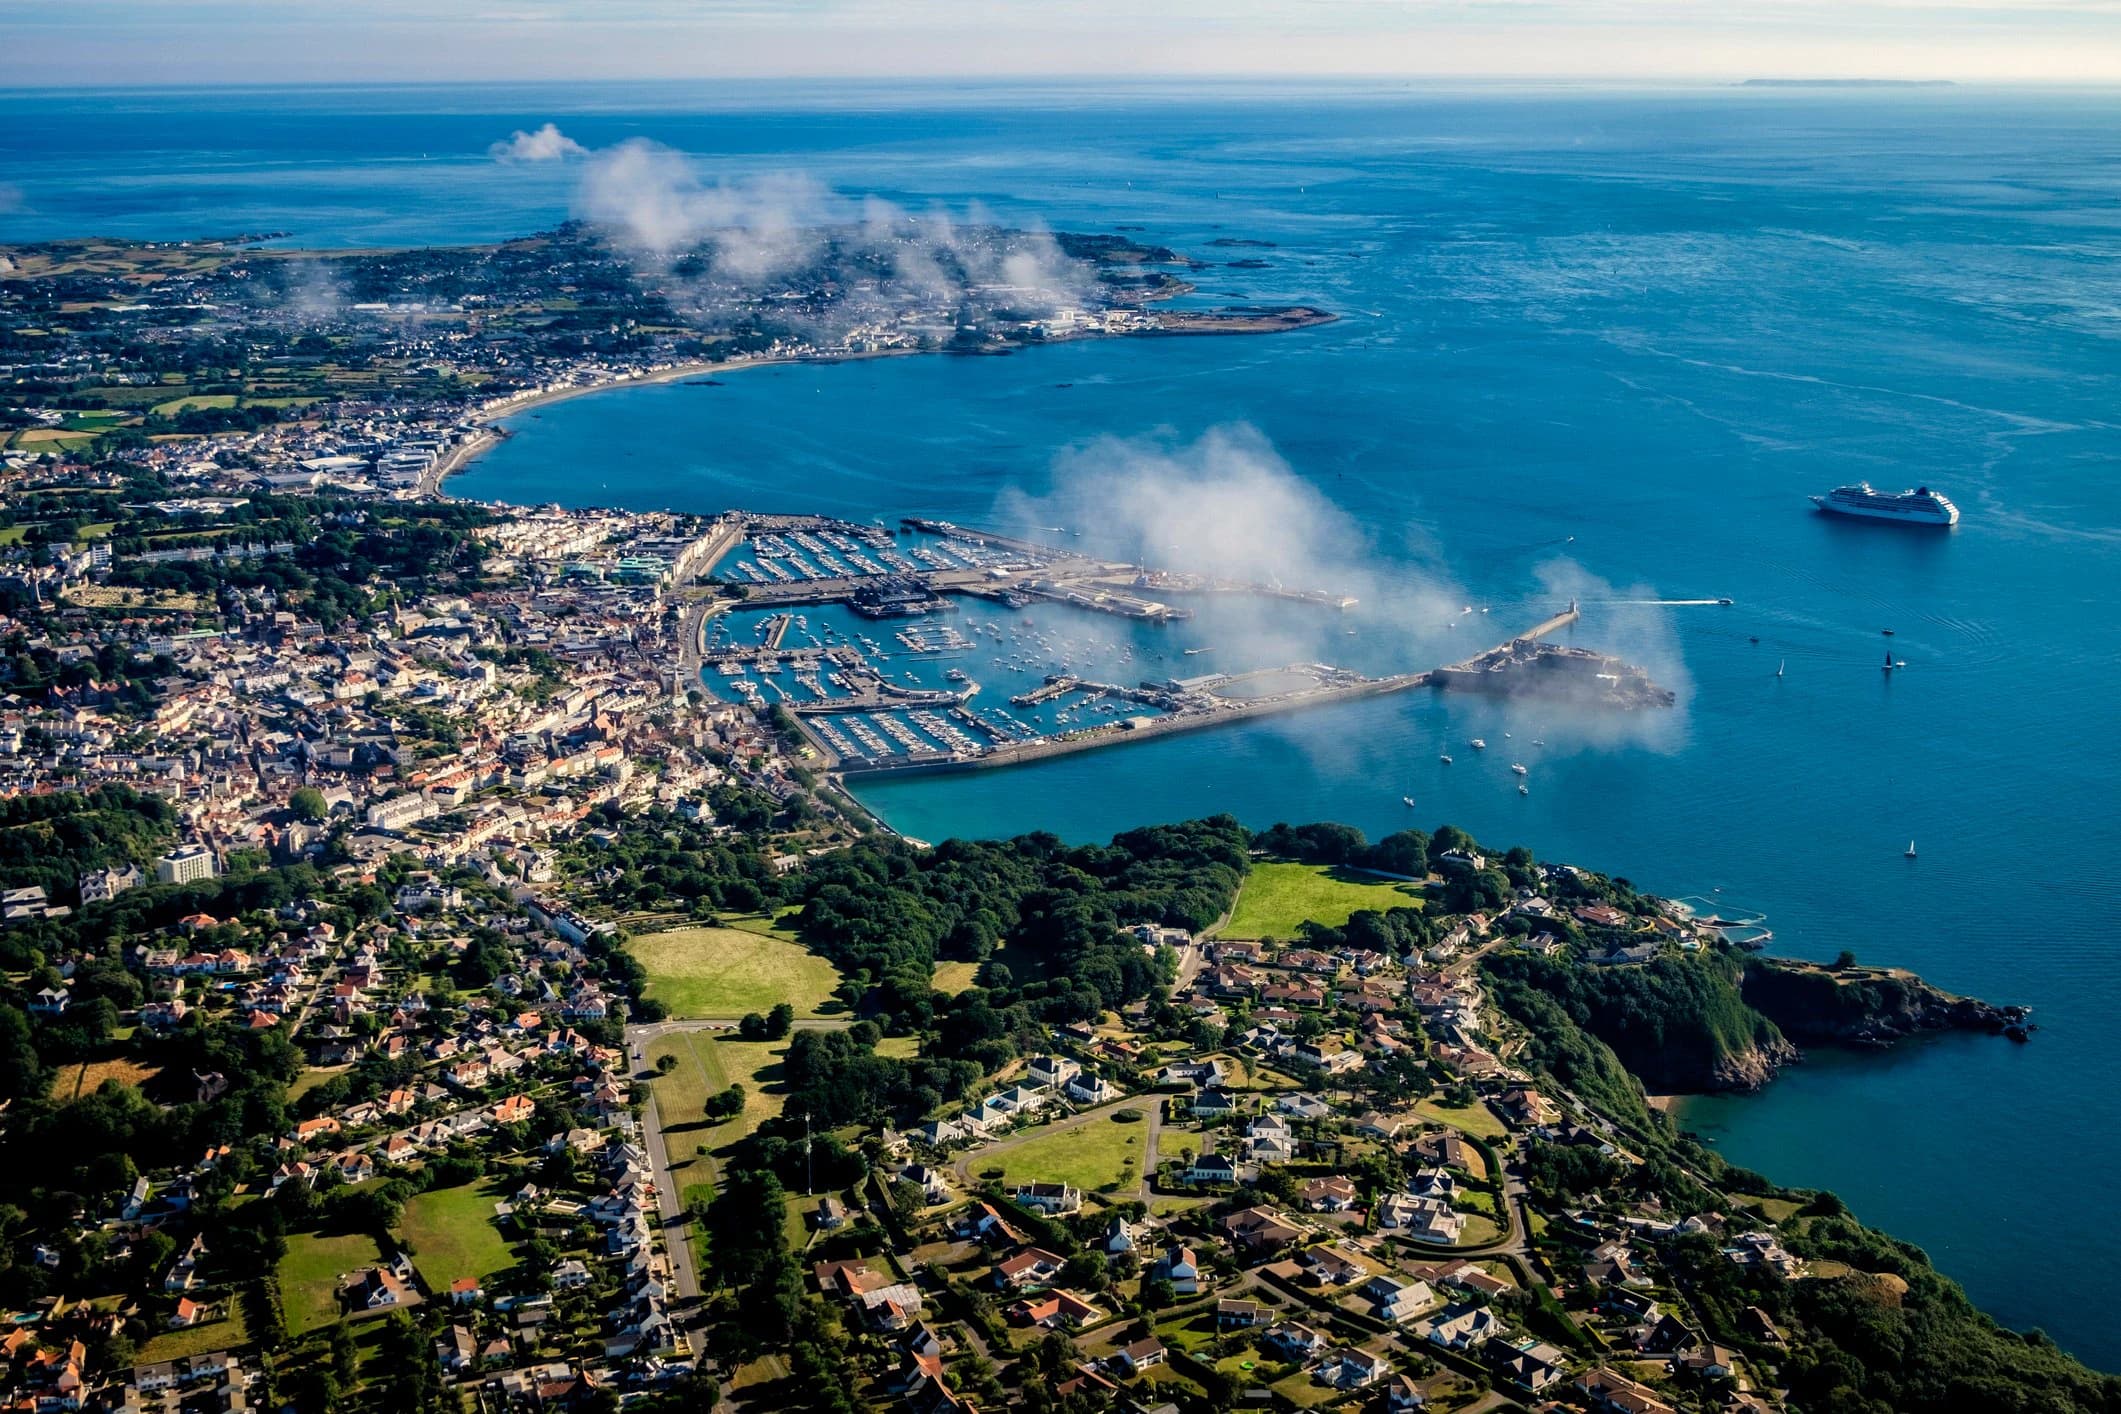
The named projects cover a wide range of current UK priorities. Immingham will gain a major freight ferry terminal. Lowestoft is being upgraded to support more offshore wind activity. Ipswich will help develop the supply chain for Sizewell C, while Solent Gateway will expand its role in trade and defence resilience.
That variety is the point and, in the process, more than 700 jobs are expected to be created or supported.
The Package Is The Point
Infrastructure investors like scale. Larger projects can justify dedicated teams, extensive due diligence and bespoke financing. Smaller upgrades often struggle to command the same attention, even when they are commercially sound or strategically important.
The ABP deal groups several investments into one programme. National Wealth Fund capital must be allocated across at least five eligible projects, creating enough scale for a substantial financing while allowing ABP to deliver smaller works across several locations.
That approach could apply well beyond ports. Networks of energy, transport, storage and industrial projects may become more investable when they are assembled under a common financing and reporting structure.
That said, making several assets behave like one programme is, of course, challenging.
Managers need a clear view of how much capital has been deployed, which project received it, whether spending meets the financing conditions and how each asset is performing. Without joined-up records, aggregation can simply replace a series of small projects with one large administrative problem.
Long-Term Assets Need Long-Term Money
The 17.5-year term is a significant part of the deal.
Ports are long-life assets, and the financing supporting them needs to reflect the period over which they will generate value. Longer-term debt can reduce refinancing pressure and give projects more time to reach their intended commercial and economic potential. The National Wealth Fund explicitly said its financing would help ABP align its debt profile with the life of the underlying projects.
Public capital can be particularly useful here. It does not need to displace commercial finance. It can provide the patience or flexibility needed to make the wider structure work.
That is what happened in this transaction. The Fund’s £200M commitment helped mobilise £100M from commercial lenders, bringing private finance into infrastructure linked to trade, energy and industrial resilience.
For infrastructure managers, the lesson is to look beyond headline pricing. Tenor, amortisation, construction timelines and projected cash flows all determine whether the financing remains suitable throughout the life of the asset.
The Work Starts After Signing
A multi-project facility creates an operational challenge from the first drawdown.
Expenditure, interest, repayments, covenants and cash movements must be tracked across several assets while preserving an accurate view of the programme as a whole. Public funding may also bring additional reporting requirements around jobs, regional growth or other policy outcomes.
Fund administration, treasury, SPV accounting, loan administration and project reporting therefore need to work from consistent information. If each asset, lender and entity follows a separate process, managers can spend more time reconciling the financing than assessing the investments.
That is why the operating model should be considered when the deal is structured, not once capital has started moving.
The ABP transaction demonstrates how public finance can give smaller projects scale, provide longer-term funding and create space for commercial lenders to participate. For infrastructure managers, the opportunity is to identify other portfolios where the same model could unlock investment.
Making those structures repeatable will depend on something less visible than the initial commitment: whether the assets, debt, cash and reporting can be managed as one coherent programme.